
Waiting until the end of the year to review your books can make tax preparation more difficult than it needs to be.
A quarterly tax preparation routine allows small businesses to review income, expenses, deductions, payroll, sales tax, estimated tax obligations, bank reconciliations, and financial reports throughout the year.
For businesses using QuickBooks Desktop, quarterly reviews can also identify bookkeeping problems before they accumulate into larger year-end issues.
The exact tax obligations depend on your business structure, location, accounting method, and tax situation. In the U.S., qualifying taxpayers may need to make federal estimated tax payments during the year. In Canada, certain individuals and corporations may have to make tax installments, while GST/HST obligations can follow a separate reporting schedule.
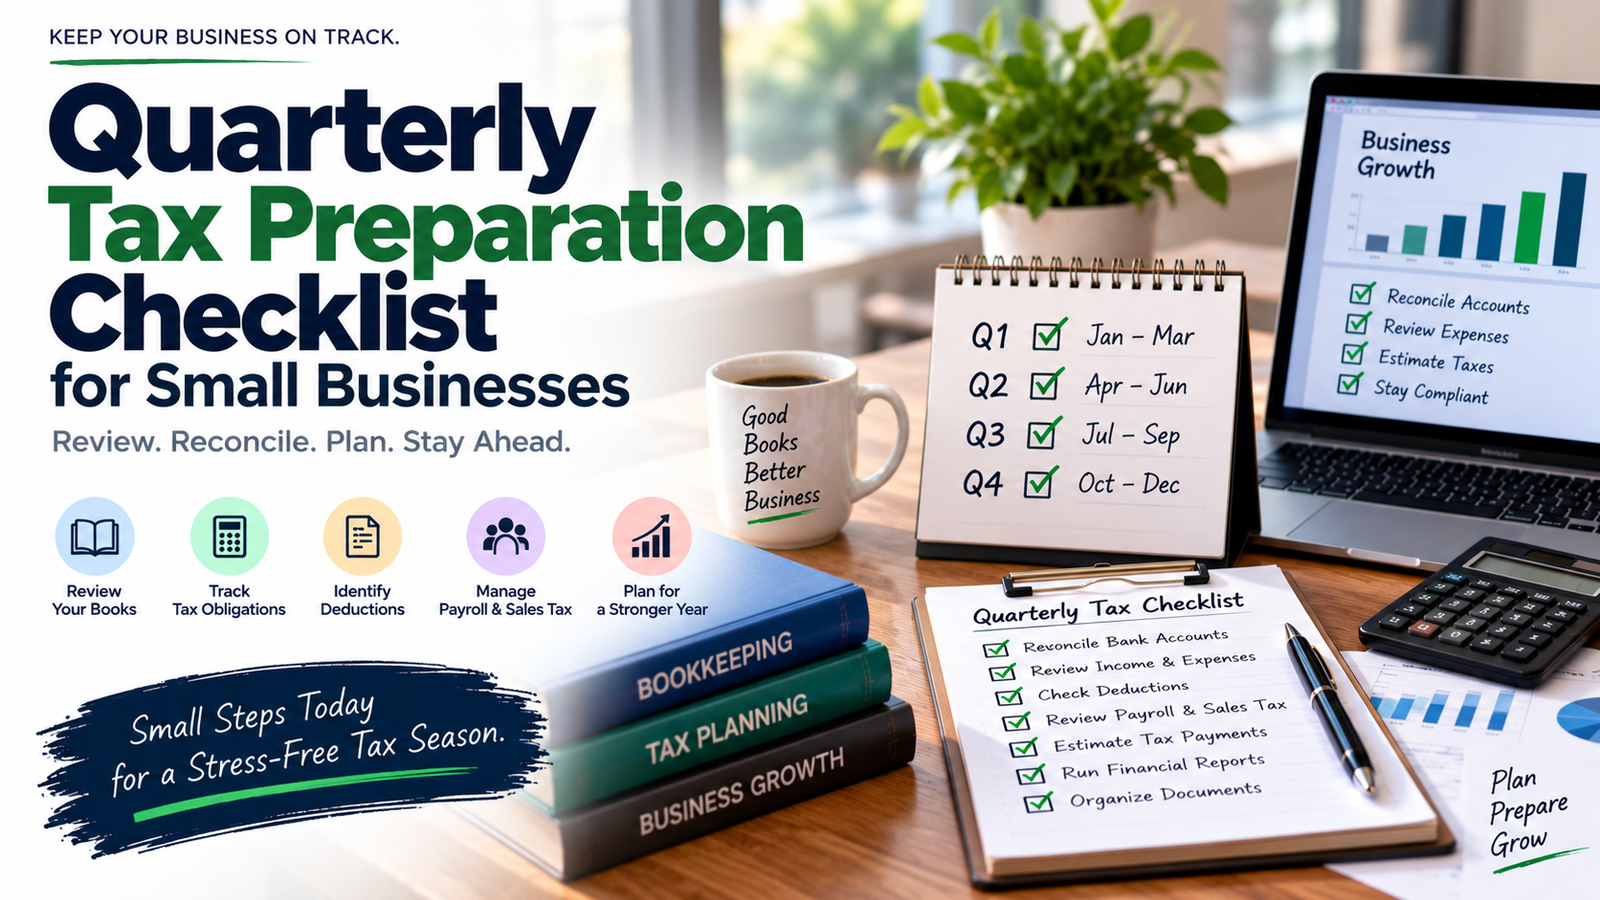
This quarterly tax preparation checklist for small businesses provides a practical framework for reviewing your records before each quarter closes.
Quick answer: Each quarter, review and reconcile your QuickBooks accounts, verify income and expenses, identify potentially deductible expenses, review payroll and sales-tax records, estimate tax obligations, update accounts receivable and payable, generate financial reports, organize supporting documents, and check upcoming filing and payment deadlines.
Quarterly Tax Preparation Checklist at a Glance
| Quarterly Task | What to Review |
| Reconcile bank accounts | Transactions, balances, outstanding items |
| Reconcile credit cards | Charges, payments, missing transactions |
| Review income | Sales, invoices, deposits, other income |
| Review expenses | Categories, duplicates, personal transactions |
| Review deductions | Potentially deductible business expenses |
| Review payroll | Wages, payroll taxes, liabilities |
| Review sales tax | Collected tax, payments, returns |
| Review contractors | Vendor payments and 1099 information |
| Review A/R | Outstanding customer invoices |
| Review A/P | Unpaid vendor bills |
| Review loans | Principal, interest, outstanding balances |
| Review fixed assets | New purchases and disposals |
| Estimate taxes | Federal/state/provincial obligations |
| Run financial reports | P&L, Balance Sheet, Cash Flow |
| Organize records | Receipts, invoices, statements, tax documents |
Why Should Small Businesses Prepare for Taxes Every Quarter?
Quarterly tax preparation does not necessarily mean filing your annual income tax return four times.
Instead, it means regularly reviewing your financial records and staying current with tax-related obligations throughout the year.
A quarterly review can help you:
- Identify missing transactions
- Catch bookkeeping errors
- Track estimated tax obligations
- Monitor profitability
- Review potentially deductible expenses
- Reconcile bank and credit card accounts
- Keep payroll records current
- Stay aware of sales-tax obligations
- Prepare better financial reports
- Reduce year-end cleanup
- Give your tax professional cleaner records
The benefit is particularly important for businesses with fluctuating income.
If revenue increases significantly during one quarter, waiting until year-end to discover the impact can make tax planning and cash management more difficult.
1. Reconcile Every Business Bank Account
Start your quarterly review by reconciling your QuickBooks bank accounts with your actual bank statements.
Review:
- Beginning balance
- Deposits
- Withdrawals
- Transfers
- Checks
- Electronic payments
- Bank fees
- Interest income
- Outstanding transactions
- Ending balance
Look for:
- Duplicate transactions
- Missing transactions
- Incorrect amounts
- Incorrect dates
- Unexplained deposits
- Transfers recorded incorrectly
- Personal transactions categorized as business expenses
A bank reconciliation is not just a bookkeeping task.
It helps establish whether the cash information appearing in your financial reports is supported by your actual bank activity.
If your QuickBooks file contains several unreconciled accounts, completing QuickBooks bookkeeping services before tax preparation can help bring the underlying records up to date.
2. Reconcile Business Credit Cards
Review every business credit card account at the end of the quarter.
Check:
- Credit card purchases
- Payments
- Refunds
- Finance charges
- Credits
- Personal transactions
- Outstanding balances
Credit card purchases can contain significant deductible business expenses, so missing or incorrectly categorized charges can affect your financial reports.
Make sure credit card balances in QuickBooks are consistent with the corresponding statements.
3. Review All Business Income
Your quarterly tax review should include a complete review of business income.
Depending on your business, compare QuickBooks records with:
- Customer invoices
- Sales receipts
- Point-of-sale reports
- Payment processor reports
- E-commerce sales
- Bank deposits
- Other income records
Look for revenue that may have been:
- Recorded twice
- Recorded in the wrong period
- Deposited but not entered
- Entered but not deposited
- Posted to the wrong account
Do not assume that every bank deposit is business revenue.
Deposits can also represent:
- Loans
- Owner contributions
- Transfers
- Refunds
- Other non-revenue transactions
Correct classification matters when preparing tax and financial reports.
4. Review Business Expenses
Go through your expense accounts each quarter.
Look for:
- Uncategorized transactions
- Duplicate expenses
- Personal purchases
- Incorrect categories
- Missing receipts
- Unusually large transactions
- Expenses recorded in the wrong period
A quarterly review is much easier than trying to review twelve months of expenses at once.
For example, if you discover that several software subscriptions have been incorrectly categorized in March, you can correct them immediately rather than trying to identify the same problem during year-end tax preparation.
5. Review Potentially Deductible Business Expenses
Quarterly tax preparation is also a good time to review expenses that may qualify as business deductions.
Depending on your circumstances, categories can include:
- Advertising
- Office expenses
- Software
- Professional fees
- Insurance
- Rent
- Utilities
- Employee wages
- Travel
- Meals
- Vehicle expenses
- Repairs
- Interest
- Business-related subscriptions
However, an expense being paid by the business does not automatically make it deductible.
For U.S. businesses, the IRS generally requires deductible business expenses to be ordinary and necessary. Personal expenses generally cannot be deducted.
Canadian businesses follow different rules, so the appropriate tax treatment should be determined under CRA requirements.
For a broader review of expense categories, use a small business tax deductions guide as part of your quarterly review rather than assuming every expense receives the same treatment.
6. Review Accounts Receivable
Run an Accounts Receivable Aging report.
Review:
- Current invoices
- 1–30 day balances
- 31–60 day balances
- 61–90 day balances
- 90+ day balances
Ask:
- Which customers have not paid?
- Are old invoices still collectible?
- Were payments applied correctly?
- Are any invoices duplicated?
- Are customer credits properly recorded?
A growing A/R balance can affect cash flow even when revenue appears strong.
This makes A/R review useful for both tax preparation and financial management.
7. Review Accounts Payable
Next, review Accounts Payable.
Look for:
- Unpaid vendor bills
- Duplicate bills
- Vendor credits
- Payments not applied correctly
- Old balances
- Bills recorded in the wrong period
A/P can also help explain why cash flow differs from reported profit.
Make sure old balances are legitimate and supported by vendor records.
8. Review Payroll and Payroll Tax Records
If you have employees, review payroll every quarter.
Check:
- Gross wages
- Federal withholding
- State withholding
- Social Security and Medicare
- Employer payroll taxes
- Payroll liabilities
- Payroll payments
- Payroll tax filings
Compare payroll reports with the amounts recorded in QuickBooks.
Investigate old payroll liability balances instead of allowing them to accumulate.
Payroll obligations have their own filing and payment schedules, so your quarterly tax checklist should not treat payroll as simply another operating expense.
9. Review Contractor and 1099 Records
If your business pays independent contractors, review vendor records throughout the year rather than waiting until January.
Check:
- Vendor names
- Addresses
- Taxpayer information
- W-9 records
- Vendor classifications
- Payments
- Payment account mapping
Quarterly review makes it easier to identify contractors whose records are incomplete.
It also helps prevent the year-end 1099 process from becoming a last-minute cleanup project.
If you use QuickBooks Desktop for contractor reporting, maintain your vendor information throughout the year instead of waiting until your 1099 filing process in QuickBooks begins.
10. Review Sales Tax and GST/HST Obligations
Income tax is not the only tax obligation a small business may have.
Depending on your location and registration status, you may need to review:
- Sales tax
- State sales tax
- Provincial sales tax
- GST
- HST
- PST
- Other applicable indirect taxes
In Canada, GST/HST reporting periods can be monthly, quarterly, or annual, depending on the business’s filing requirements. CRA states that quarterly GST/HST filers generally file and pay one month after the end of the reporting period.
Review:
- Tax collected
- Tax paid
- Input tax credits, where applicable
- Sales-tax liabilities
- Previous payments
- Returns filed
- Outstanding balances
Do not confuse sales tax collected from customers with business revenue.
11. Review Estimated Tax or Tax Installments
This is one of the most important quarterly tasks.
U.S. businesses
Depending on the taxpayer and business structure, estimated tax payments may be required during the year.
The IRS divides the estimated-tax year into four payment periods, with general due dates of:
| Payment period | General due date |
| January 1–March 31 | April 15 |
| April 1–May 31 | June 15 |
| June 1–August 31 | September 15 |
| September 1–December 31 | January 15 of the following year |
These dates are general federal estimated-tax dates; special rules can apply to fiscal-year taxpayers, farmers, fishers, and other situations.
Not every small business makes estimated payments in the same way.
The applicable obligation depends on the taxpayer, business structure, income, withholding, and other factors.
Canadian businesses
Canadian tax installment rules are different.
For individuals with business, professional, or commission income who are required to make installments, CRA lists March 15, June 15, September 15, and December 15 as the 2026 payment dates.
Corporate installments follow different rules. Corporations generally pay monthly installments, although eligible Canadian-controlled private corporations can qualify for quarterly installments. The due dates are tied to the corporation’s fiscal year rather than simply using the U.S. quarterly schedule.
Important
Do not copy a U.S. estimated-tax calendar and apply it to a Canadian business.
Your payment schedule can depend on:
- Business structure
- Tax year
- Residence
- Prior-year tax
- Current-year tax
- Filing status
- Applicable tax authority
Always confirm current deadlines with the IRS, CRA, or your tax professional.
12. Review Your Tax Liability Estimate
A quarterly review should not only ask whether a payment is due.
It should also ask whether your estimated tax position has changed.
Compare:
- Current revenue
- Current expenses
- Current profit
- Prior-quarter results
- Prior-year results
- Estimated tax payments already made
- Expected full-year income
If your business is growing rapidly, your expected tax liability may also change.
Conversely, a major decline in revenue may change your projected liability.
Your tax professional can help determine whether estimated payments should be adjusted under the applicable rules.
13. Review Fixed Assets and Major Purchases
Review equipment and other significant purchases made during the quarter.
Examples include:
- Computers
- Machinery
- Vehicles
- Furniture
- Equipment
- Property
- Major improvements
Do not automatically categorize every large purchase as an ordinary expense.
Some purchases may need to be treated as capital assets and depreciated or otherwise recovered under applicable tax rules.
Maintain:
- Purchase date
- Purchase amount
- Invoice
- Proof of payment
- Description
- Business-use information
- Financing information
A quarterly asset review makes year-end depreciation and tax preparation easier.
14. Review Business Loans and Interest
If your business has loans or lines of credit, review the balances each quarter.
Separate:
- Principal repayments
- Interest
- Loan fees
- New borrowing
- Refinancing
- Transfers
Compare QuickBooks balances with lender statements.
This also helps ensure your Balance Sheet is accurate.
If you are preparing for financing or want to monitor business performance, keeping accurate business financial reports throughout the year can make it easier to understand debt, cash flow, profitability, and working capital.
15. Review Owner Transactions
Small businesses frequently mix owner transactions with operating activity.
Review:
- Owner contributions
- Owner draws
- Distributions
- Personal purchases
- Reimbursements
- Transfers between personal and business accounts
Do not automatically categorize an owner withdrawal as a business expense.
The appropriate treatment depends on the business structure and circumstances.
Keeping these transactions separate makes your financial reports easier to understand and reduces year-end cleanup.
16. Review Your QuickBooks Financial Reports
At the end of each quarter, generate a basic financial reporting package.
At minimum, consider reviewing:
Profit and Loss Statement
Shows revenue and expenses during the quarter and year-to-date.
Balance Sheet
Shows assets, liabilities, and equity at the end of the quarter.
Cash Flow Statement
Helps explain how cash moved during the period.
Accounts Receivable Aging
Shows outstanding customer balances.
Accounts Payable Aging
Shows outstanding vendor obligations.
General Ledger
Provides transaction-level detail.
These reports can reveal issues that are difficult to identify by looking at individual bank transactions.
If your business needs organized reports for management, lenders, investors, or tax professionals, professionally prepared business financial reports can provide a cleaner view of the company’s financial position.
17. Compare the Current Quarter With the Previous Quarter
Quarterly preparation should include trend analysis.
Compare:
- Revenue
- Gross profit
- Operating expenses
- Net income
- Cash
- Accounts receivable
- Accounts payable
- Debt
- Major expense categories
Ask:
- Why did revenue increase or decrease?
- Why did expenses change?
- Are margins improving?
- Is cash flow becoming tighter?
- Are customers taking longer to pay?
- Has debt increased?
- Are there unusual transactions?
This turns quarterly tax preparation into a useful business-management process.
18. Organize Receipts and Supporting Documents
Do not wait until tax season to organize documentation.
Maintain records for:
- Receipts
- Invoices
- Bank statements
- Credit card statements
- Contracts
- Payroll records
- Loan statements
- Asset purchases
- Mileage records
- Business travel
- Meals
- Tax payments
- Sales-tax filings
The IRS states that taxpayers should keep records that support income, deductions, and credits reported on their tax returns. The CRA likewise requires supporting documentation for business expense claims.
Digital organization can make the year-end process considerably easier.
19. Check for Missing or Uncategorized Transactions
Before closing the quarter, run through your QuickBooks transaction list.
Search for:
- Uncategorized expenses
- Uncategorized income
- Uncategorized deposits
- Duplicate transactions
- Unmatched bank-feed transactions
- Old unreconciled items
- Transactions with unclear descriptions
Do not simply assign an unknown transaction to an expense category to make the books look complete.
Investigate it first.
20. Prepare a Quarterly Tax File
Create a folder for each quarter.
For example:
Q1
- Bank statements
- Credit card statements
- Payroll reports
- Sales-tax reports
- Tax payments
- Financial reports
- Receipts
- Major purchase documents
Repeat the process for Q2, Q3, and Q4.
By year-end, most of the supporting documentation will already be organized.
Quarterly Tax Preparation Checklist by Quarter
The basic workflow stays similar throughout the year, but the emphasis can change.
Q1 Tax Preparation Checklist
Focus on establishing clean records for the new tax year.
- Confirm opening balances
- Reconcile bank accounts
- Reconcile credit cards
- Review prior-year carryovers
- Review estimated tax obligations
- Review payroll
- Review sales tax/GST/HST
- Set up expense categories correctly
- Organize Q1 documentation
- Generate Q1 financial reports
Q1 is also a good time to resolve bookkeeping issues inherited from the previous year.
Q2 Tax Preparation Checklist
By Q2, focus on identifying trends.
- Reconcile all accounts
- Review revenue growth
- Review expense changes
- Update estimated tax calculations
- Review contractor payments
- Review payroll liabilities
- Review sales tax/GST/HST
- Review A/R and A/P
- Review major purchases
- Compare Q2 with Q1
If profitability has changed significantly, discuss the potential tax implications with your tax professional.
Q3 Tax Preparation Checklist
Q3 is an important planning point because the year is approaching its final quarter.
- Reconcile all accounts
- Review year-to-date profit
- Review estimated tax payments
- Review deductions
- Review contractor records
- Review payroll
- Review fixed assets
- Review loans
- Review A/R and A/P
- Identify year-end bookkeeping issues early
This is a good time to identify problems that could become difficult to resolve in Q4.
Q4 Tax Preparation Checklist
Q4 should focus on year-end readiness.
- Complete all bank reconciliations
- Reconcile credit cards
- Review full-year income
- Review full-year expenses
- Identify capital purchases
- Review payroll
- Review contractor records
- Review tax payments
- Review sales tax/GST/HST
- Review A/R and A/P
- Generate year-end financial reports
- Organize tax documents
- Prepare records for your tax professional
Your Q4 review should become the foundation for annual tax preparation.
U.S. vs. Canada: Quarterly Tax Preparation Differences
A quarterly checklist can be used in both countries, but the tax obligations are not identical.
| Area | United States | Canada |
| Estimated income tax | Estimated payments may apply | Installments may apply |
| Individual installment dates | Generally Apr. 15, Jun. 15, Sep. 15, Jan. 15 | Generally Mar. 15, Jun. 15, Sep. 15, Dec. 15 for required individual installments |
| Corporate installments | Rules depend on entity/program | Generally monthly; eligible CCPCs may pay quarterly |
| Sales tax | State/local rules vary | GST/HST/PST rules vary |
| Payroll | Federal/state rules | Federal/provincial rules |
| Financial reporting | Lender/tax requirements vary | Lender/tax requirements vary |
| Filing schedule | Depends on entity | Depends on entity and fiscal year |
U.S. estimated-tax dates are established by the IRS for the applicable payment periods, while Canadian installment dates depend on the taxpayer or corporation and its tax year.
Common Quarterly Tax Preparation Mistakes
Waiting until year-end
The longer bookkeeping problems remain unresolved, the harder they can be to identify.
Treating every bank transaction as income or expense
Bank activity still needs to be classified correctly.
Forgetting estimated tax payments
Tax obligations can arise throughout the year rather than only when the annual return is filed.
Ignoring sales tax
Sales tax and income tax are separate obligations and may have different reporting schedules.
Mixing personal and business transactions
This can make both bookkeeping and tax preparation more difficult.
Ignoring old balance-sheet accounts
Old A/R, A/P, loan, payroll, and tax-liability balances can indicate unresolved bookkeeping problems.
Not keeping receipts
A transaction in QuickBooks does not eliminate the need for appropriate supporting documentation.
Using the wrong country’s tax calendar
U.S. and Canadian tax installment systems are different.
Do not assume that a quarterly deadline in one country applies to the other.
What Should You Give Your Tax Professional Each Quarter?
Your tax professional may request different information depending on your business and tax situation.
A useful quarterly package can include:
- Profit and Loss
- Balance Sheet
- Cash Flow Statement
- General Ledger
- Bank reconciliation reports
- Accounts Receivable Aging
- Accounts Payable Aging
- Payroll reports
- Sales-tax reports
- Contractor payment information
- Loan statements
- Major asset purchase records
- Tax payment records
- Supporting documentation
If your records are maintained in QuickBooks, providing organized QuickBooks financial reports can make it easier for your tax professional to review your business activity.
What If Your Books Are Not Ready for Quarterly Tax Preparation?
Do not ignore bookkeeping problems until year-end.
If your QuickBooks file contains:
- Unreconciled bank accounts
- Uncategorized transactions
- Duplicate transactions
- Incorrect expense classifications
- Old A/R balances
- Old A/P balances
- Incorrect loan balances
- Payroll liability problems
- Missing income
- Damaged company-file data
Identify the underlying issue before relying on the reports.
For routine bookkeeping problems, professional QuickBooks bookkeeping services can help reconcile accounts, organize transactions, and maintain cleaner books throughout the year.
If your QuickBooks company file has a technical or data-integrity problem, the underlying file may need to be addressed separately before the financial information can be relied upon.
When Should You Start Quarterly Tax Preparation?
You do not have to wait until the quarter ends.
A practical workflow is:
Throughout the quarter:
Record transactions and retain documentation.
During the final month:
Review income and expenses and identify unusual transactions.
After quarter-end:
Reconcile accounts and finalize the quarter’s books.
Before payment or filing deadlines:
Confirm tax obligations and required payments or filings.
After the quarter is complete:
Save financial reports and supporting documentation.
This creates a continuous process rather than a stressful tax-season cleanup.
Frequently Asked Questions
What is a quarterly tax preparation checklist?
A quarterly tax preparation checklist is a recurring review of business books, tax obligations, deductions, payroll, sales tax, financial reports, and supporting documents. It helps businesses stay organized throughout the year instead of waiting until annual tax preparation.
Do small businesses have to pay taxes quarterly?
Not every small business has the same quarterly tax obligation. U.S. taxpayers who meet the requirements may need estimated tax payments, while Canadian individuals and corporations can have tax installment obligations under different rules.
What should I check in QuickBooks every quarter?
At minimum, review bank and credit card reconciliations, income, expenses, Accounts Receivable, Accounts Payable, payroll, loans, fixed assets, tax liabilities, and financial reports.
What financial reports should a small business run quarterly?
Common reports include Profit and Loss, Balance Sheet, Cash Flow Statement, General Ledger, Accounts Receivable Aging, and Accounts Payable Aging.
Should I reconcile QuickBooks every quarter?
Yes. Regular reconciliation helps identify missing, duplicate, or incorrectly recorded transactions before they accumulate into larger year-end problems.
What records should I keep for quarterly tax preparation?
Keep receipts, invoices, bank statements, credit card statements, payroll records, tax payment confirmations, sales-tax records, loan statements, asset purchase records, and other documentation supporting your financial activity.
How are U.S. and Canadian quarterly tax payments different?
They follow different systems. U.S. federal estimated-tax payment periods generally use April 15, June 15, September 15, and January 15 of the following year. Canadian installment dates depend on the taxpayer or corporation; required individual installments commonly fall on March 15, June 15, September 15, and December 15, while corporate quarterly installments for eligible CCPCs are tied to the corporation’s fiscal year.
Can QuickBooks calculate my quarterly taxes?
QuickBooks can organize financial data and produce reports that help with tax preparation, but the amount you owe depends on applicable tax rules, business structure, income, deductions, credits, prior payments, and other factors. Do not assume a QuickBooks report alone determines your final tax liability.
What if I missed a quarterly tax payment?
Do not ignore it. Review the applicable tax authority’s rules, determine whether a payment or filing is outstanding, and speak with your tax professional about the appropriate next step. Late or insufficient estimated payments can result in interest or penalties in some situations.
Quarterly Tax Preparation Checklist for Small Businesses
Before considering each quarter complete, verify:
QuickBooks and bookkeeping
- Bank accounts reconciled
- Credit cards reconciled
- Transactions categorized
- Duplicate transactions removed
- Uncategorized transactions reviewed
- Personal transactions separated
Income
- Sales reviewed
- Customer payments reviewed
- Deposits reconciled
- Other income reviewed
Expenses
- Business expenses reviewed
- Potential deductions identified
- Large purchases reviewed
- Capital expenses identified
- Supporting receipts retained
Payroll and contractors
- Payroll reconciled
- Payroll liabilities reviewed
- Contractor records reviewed
- W-9 information maintained
- 1099-related payments reviewed
Taxes
- Estimated tax/installment obligation reviewed
- Prior payments verified
- Sales tax/GST/HST reviewed
- Payroll tax obligations reviewed
- Upcoming deadlines checked
Financial reports
- Profit and Loss reviewed
- Balance Sheet reviewed
- Cash Flow reviewed
- A/R Aging reviewed
- A/P Aging reviewed
- General Ledger reviewed
Documentation
- Bank statements saved
- Credit card statements saved
- Receipts saved
- Invoices saved
- Tax payment confirmations saved
- Loan statements saved
- Asset records saved
Final Takeaway
A quarterly tax preparation routine helps small businesses stay ahead of bookkeeping problems, tax payments, deductions, payroll obligations, and financial reporting.
The process is straightforward:
Record → Reconcile → Review → Estimate → Document → Report
For U.S. businesses, this can include reviewing federal estimated-tax obligations. For Canadian businesses, it may include income-tax installments, GST/HST obligations, and other federal or provincial requirements. The specific deadlines depend on the taxpayer, business structure, tax year, and filing requirements.
The most important step is consistency.
Instead of waiting until tax season to discover missing transactions, unreconciled accounts, or incomplete documentation, review your QuickBooks records every quarter.
If your books are accurate and your financial reports are current, your tax professional has a much cleaner starting point for year-end tax preparation.
If your business needs help maintaining organized books, preparing financial reports, or handling tax-related accounting work, professional taxation services can help you build a more consistent process throughout the year.
Tax rules and deadlines can change, and requirements differ between the U.S. and Canada. Always verify current filing and payment requirements with the IRS, CRA, or a qualified tax professional.
This version deliberately uses contextual internal-link anchors inside the article itself rather than adding a separate “internal links” section. It also keeps the Taxation service as the main commercial destination, while the bookkeeping and financial-report services support the quarterly workflow naturally.
Sources:
https://www.irs.gov/faqs/estimated-tax
https://www.canada.ca/en/revenue-agency/services/forms-publications/publications/t4002/t4002-3.html